
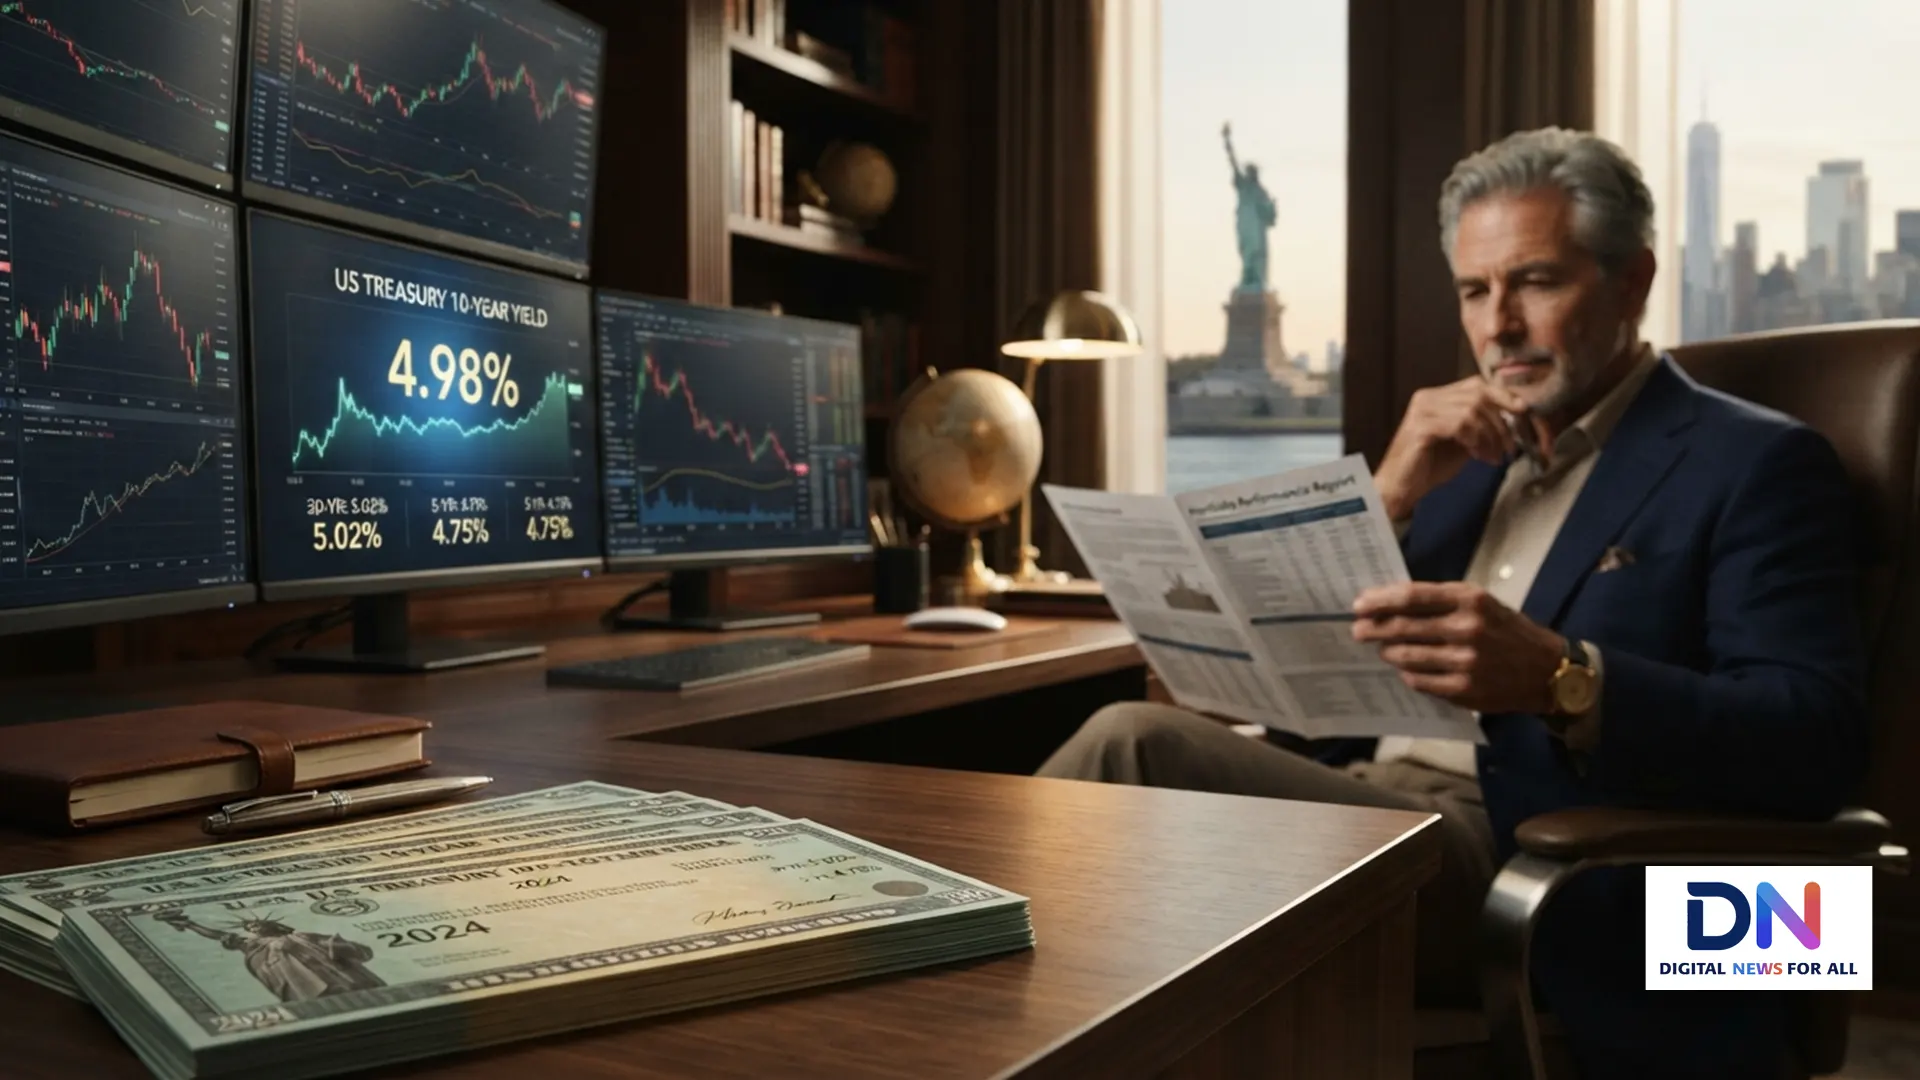
The 5% Treasury yield has returned as one of the biggest stories in the bond market. For retirees and investors approaching retirement, higher government-bond yields can create an opportunity for more predictable income. But the headline yield does not eliminate risk. Inflation, interest-rate changes, taxes and the timing of withdrawals can all affect the real outcome.
The 5% Yield Is Back
The U.S. 10-year Treasury yield moved around the 5% level in September 2026. On September 21, the yield stood at approximately 4.96%, according to Forbes Advisor.
The yield had recently moved above 5%, reaching levels not seen since the years before the financial crisis. Reuters reported that investors had become more comfortable with the higher-yield environment as economic growth and corporate earnings remained relatively resilient.
Why Retirees Are Paying Attention
Higher Treasury yields can change the mathematics of retirement income. Investors who previously needed larger allocations to riskier assets to generate income may now have more fixed-income options.
A 5% nominal yield on $500,000 would equal $25,000 in annual interest before taxes, assuming the investment actually earns that yield and the principal remains invested. However, that calculation does not account for inflation, taxes or changes in the value of a bond sold before maturity.
Investor.gov notes that bonds carry interest-rate and inflation risks. A bond sold before maturity can be worth more or less than its face value.
The Hidden Trap: A High Yield Is Not the Same as a Safe Portfolio
The phrase “5% Treasury yield” can sound like a guaranteed 5% portfolio return. It is not.
Longer-duration Treasury securities can decline in market value when interest rates rise. That matters for retirees who may need to sell investments to fund living expenses rather than holding every security until maturity.
JPMorgan Chase notes that higher Treasury yields can provide opportunities for income-focused investors while also creating pressure on existing bond prices.
Inflation Can Still Eat Into Income
A nominal 5% return does not necessarily translate into a 5% increase in purchasing power.
If inflation remains elevated, retirees may find that their fixed interest income buys fewer goods and services over time. This becomes especially important for people expecting retirement to last two or three decades.
Investor.gov identifies inflation as a fundamental investment risk because rising prices reduce the purchasing power of fixed payments.
The Fed and Oil Could Keep Moving Yields
The Federal Reserve remains a major influence on the interest-rate environment. The Fed raised its policy rate by 25 basis points in September 2026, taking the target range to 3.75%–4.00%.
Meanwhile, energy prices and geopolitical developments have contributed to inflation concerns. MarketWatch reported that the 10-year Treasury yield moved below 5% as oil prices retreated on September 22.
What Retirement Investors Should Watch
The new yield environment makes several portfolio questions more important. Investors need to consider the duration of their bonds, their expected withdrawal schedule, inflation exposure and the tax treatment of their income.
A diversified retirement portfolio can contain multiple maturity dates rather than relying entirely on long-duration securities. A ladder of individual Treasury securities is one possible approach, while Treasury funds provide a different combination of liquidity and interest-rate exposure.
Cash reserves can also matter because having money available for near-term expenses may reduce the need to sell longer-term investments during a market decline.
The New Normal Is About More Than 5%
The return of higher Treasury yields changes the choices available to retirement investors, but it does not eliminate the need for diversification and risk management.
The key question is not simply whether the 5% Treasury yield is attractive. It is how that yield fits into an individual’s time horizon, income needs, inflation expectations, taxes and tolerance for market fluctuations.
For retirees, higher yields can provide an important source of income. But treating a headline yield as a complete retirement strategy could create a different kind of trap: concentrating too much money in one asset class while overlooking the risks that remain.
#TreasuryYields #RetirementPlanning #Bonds #Investing #RetirementIncome #FederalReserve #InterestRates #PersonalFinance